Imagine a bank that moves billions across borders every day. Payments leave in dollars, euros, yen, and rupees. Each one passes through a chain of correspondent banks before it reaches its destination. Now imagine that, at the end of the day, nobody can say with certainty whether every one of those payments landed where it should. That is not a hypothetical nightmare. It is the exact problem nostro reconciliation exists to solve.
It is one of the most critical, and most underestimated, controls in international banking. In this guide, we unpack what nostro reconciliation is, why it is so hard, what goes wrong, and how modern automated reconciliation is rewriting the rules.
What Is a Nostro Account?
The word nostro comes from the Latin for “ours.” A nostro account is an account that a bank holds with another bank, usually abroad, in that country’s local currency.
For example, an Indian bank that needs to settle US dollar payments may keep a USD account with a bank in New York. From the Indian bank’s point of view, that is its nostro (“our account with you”). From the New York bank’s point of view, the same account is a vostro (“your account with us”).
These accounts are the plumbing of correspondent banking. They let banks settle foreign currency transactions without needing a branch in every country. Every cross-border payment, trade settlement, foreign exchange (FX) deal, and securities transaction that touches a foreign currency usually leaves a trace in a nostro account.
What Is Nostro Reconciliation?
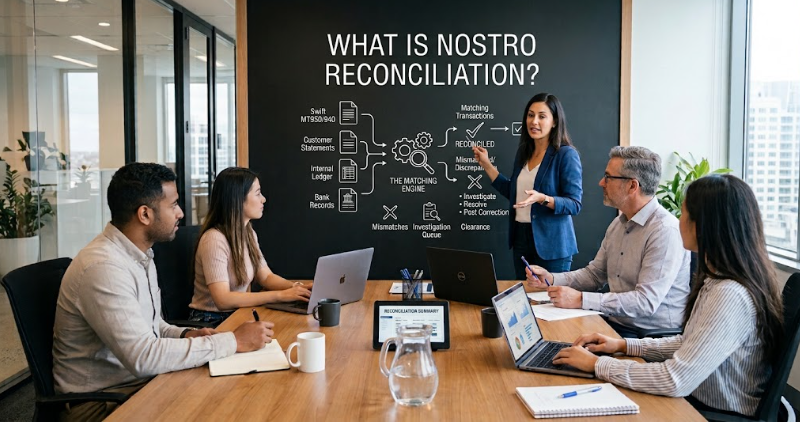
Nostro reconciliation is the process of comparing a bank’s internal records of its nostro account against the statement sent by the correspondent bank, and resolving any differences.
In simple terms, it answers one question every day: “Does what we think happened in this account match what the other bank says happened?”
The two sides of the comparison are:
- Your ledger: the entries recorded in your general ledger or treasury, payments, and settlement systems
- The external statement: typically a SWIFT MT950 (statement message), MT940 (customer statement), or the newer camt.053 ISO 20022 format sent by the correspondent bank
Every debit, credit, fee, and balance should agree. When they do not, there is a “break,” and that break needs to be investigated.
Why Nostro Reconciliation Matters So Much
It may sound like back-office housekeeping, but nostro reconciliation protects some of the biggest risks a bank faces.
1. Liquidity and cash management
Treasury teams decide how much money to hold in each currency and each account. If balances are wrong, they may leave too much idle cash in one place, which is costly, or too little in another, which risks overdrafts and failed payments.
2. Financial loss prevention
Unmatched items can hide duplicate payments, missing credits, wrong amounts, or incorrect charges. The longer they sit, the harder they are to recover.
3. Fraud and operational risk detection
Unauthorized debits and suspicious entries tend to surface during reconciliation. Daily matching helps catch them before they grow.
4. Regulatory compliance
Regulators expect banks to maintain strong internal controls and accurate books. Aged, unresolved items attract scrutiny from auditors and supervisors, and can trigger provisions or capital implications.
5. Customer trust
When a client’s payment goes missing in the chain, their bank is the one they blame. Timely reconciliation helps resolve issues before customers notice.
6. Accurate financial reporting
Nostro balances feed directly into the balance sheet and profit and loss statement. Errors flow straight into reported numbers.
How the Nostro Reconciliation Process Works
While each bank has its own variations, the core workflow looks like this:
Step 1: Collect the data. Gather internal ledger entries and the correspondent bank’s statements for each nostro account, usually every day.
Step 2: Standardize the formats. Statements arrive in different formats, such as MT940, MT950, camt.053, or even PDFs and spreadsheets from smaller institutions. Data must be cleaned and normalized so it can be compared.
Step 3: Match the entries. Match each internal entry to the corresponding external entry using fields such as amount, value date, currency, and reference numbers. Many matches are straightforward one-to-one. Others are one-to-many or many-to-many, for example, one bulk credit covering several customer payments.
Step 4: Identify unmatched items. Anything that does not match is flagged as an exception, or “break.”
Step 5: Investigate and resolve. Operations staff trace each break to its cause. They may contact the correspondent bank, check the payment system, correct an internal posting, or raise a claim.
Step 6: Post adjustments. Where needed, journal entries are made to correct the books.
Step 7: Age and escalate. Unresolved items are tracked by age, and older breaks are escalated before they become write-offs.
Step 8: Report and sign off. Management receives reports on break volumes, values, and aging, and supervisors approve the reconciliation.
Why Do Nostro Breaks Happen?
Understanding the usual suspects makes them easier to prevent. Common causes include:
- Timing differences: a payment is recorded on one day by your bank and the next day by the correspondent, often because of time zones and cut-off times
- Missing or late statements: the correspondent’s statement arrives late, incomplete, or not at all
- Reference mismatches: payment references are truncated, altered, or missing as messages pass through intermediaries
- Duplicate entries: the same payment is posted twice
- Incorrect amounts or currency: keying errors, FX conversion differences, or deducted fees
- Unrecorded charges and interest: bank fees or interest appear on the statement before they appear in your books
- Failed or returned payments: a payment is rejected or returned, but the internal record is not updated
- Manual posting errors: transactions entered incorrectly by staff
- Fraud or unauthorized activity: rare, but costly when missed
The Challenges Banks Face
If nostro reconciliation were simple, nobody would write guides about it. Here is why it is genuinely hard.
Sky-high volumes
Large banks may handle hundreds of nostro accounts across dozens of currencies and thousands of daily entries. Matching that volume by eye or with spreadsheets is unrealistic.
Multiple formats and sources
Every correspondent bank, region, and payment system can use slightly different formats and conventions. Normalizing data is a project in itself.
Complex matching scenarios
Bulk payments, netted settlements, and split transactions do not match neatly one-to-one. Rule-building gets complicated fast.
Time pressure
Treasury needs accurate positions early in the day. A reconciliation that finishes at 4 p.m. may be too late to act on.
Aged and unresolved items
Breaks that are not resolved quickly become harder to investigate, as memories fade and documentation gets lost. Aged items can eventually become write-offs.
Limited visibility
When data lives in spreadsheets and emails, managers struggle to see which accounts are clean, which are behind, and where the risk is concentrated.
Rising cost and operational risk
The more manual the process, the more people it takes, and the more room there is for human error.
Evolving standards
The industry shift to ISO 20022 brings richer data, which is a major opportunity. But it also means banks must handle both legacy and new formats during the transition.
Best Practices for Nostro Reconciliation
Whether or not you automate, these principles help:
- Reconcile daily. Daily reconciliation catches issues while they are fresh and keeps breaks small.
- Reconcile intraday where possible. Near real-time matching improves liquidity decisions.
- Prioritize by value and risk. Focus on high-value breaks and high-risk accounts first.
- Set clear aging thresholds. Define when items must be resolved or escalated.
- Standardize investigation workflows. Clear ownership and templates avoid delays.
- Maintain strong correspondent relationships. Fast communication with partner banks speeds up resolution.
- Track root causes. Fixing recurring causes is better than clearing the same breaks again and again.
- Keep an audit trail. Document every action, adjustment, and approval.
- Separate duties. The person who posts entries should not be the one who approves reconciliations.
Why Manual Nostro Reconciliation Is Running Out of Road
For years, banks have patched together spreadsheets, macros, and legacy in-house tools. These solutions often grow organically, are poorly documented, and depend on a few experienced individuals. When those people leave, the knowledge goes with them.
As payment volumes grow, instant payments expand, and ISO 20022 reshapes data, these approaches struggle to keep up. The cost is not just time. It is delayed decisions, trapped liquidity, aged breaks, and audit findings.
How Automated Nostro Reconciliation Works
Automated nostro reconciliation uses software to ingest, normalize, and match data at scale, then surfaces only the items that need human attention. A modern platform typically provides:
- Automated data ingestion. Statements and ledger data are pulled in automatically from SWIFT, bank portals, core banking, and treasury systems in multiple formats.
- Data normalization. Different formats are converted into a common structure, so everything can be compared accurately.
- Rules-based and intelligent matching. Configurable rules handle one-to-one, one-to-many, and many-to-many matches. Smarter engines can learn from past matches and tolerate small differences in references or dates.
- Exception management. Breaks are automatically categorized, prioritized, and routed to the right team with the context needed to resolve them.
- Aging and escalation workflows. Items approaching thresholds trigger alerts so nothing slips through.
- Dashboards and analytics. Real-time views show match rates, break values, aging profiles, and trends by account, currency, or correspondent.
- Audit trail and controls. Every action is logged, with role-based access and approvals built in.
The shift is profound. Instead of spending the day finding matches, teams spend it resolving exceptions and preventing them in the first place.
The Benefits of Automating Nostro Reconciliation
- Higher straight-through matching. The vast majority of entries can be matched automatically, leaving a much smaller exception pool.
- Faster, earlier reconciliation. Results are ready sooner, giving treasury a clearer cash position when it matters.
- Reduced operational risk. Consistent rules replace manual keying and copy-paste errors.
- Lower cost per transaction. Teams can handle growing volumes without proportionally growing headcount.
- Fewer aged breaks and write-offs. Quick detection and escalation protect the bottom line.
- Improved liquidity management. Accurate balances reduce excess buffers and avoid shortfalls.
- Stronger audit and regulatory readiness. Complete trails and consistent reports make reviews smoother.
- Better visibility. Managers can finally see risk by account, currency, and counterparty in real time.
- Happier teams. Skilled operations staff move from repetitive matching to higher-value investigation and analysis.
What to Look for in a Nostro Reconciliation Solution
When evaluating platforms, consider:
- Format coverage: support for MT940, MT950, camt.053, and custom or legacy formats
- Matching flexibility: one-to-one, one-to-many, many-to-many, and tolerance-based matching
- Scalability: the ability to handle high volumes and many accounts without slowing down
- Workflow tools: exception assignment, commentary, aging, and escalation
- Integration: connectivity with core banking, treasury, payment hubs, and general ledger
- Reporting and analytics: real-time dashboards and management information
- Controls and security: audit trails, role-based access, and strong data protection
- Quick deployment: faster time to value with low reliance on heavy IT projects
- Future readiness: support for ISO 20022 and evolving payment standards
Real-World Scenario: From Chaos to Clarity
Consider a mid-sized bank with 150 nostro accounts across 25 currencies. Every morning, a team of analysts downloads statements, pastes them into spreadsheets, and starts matching. By midday, they are still working through the largest accounts. Breaks accumulate, some for weeks. Treasury, unsure of true balances, holds extra cash as a buffer.
Now picture the same bank with automation. Statements flow in overnight. By the time the team logs in, most entries have been matched. The dashboard shows a short, prioritized list of exceptions, with the oldest and largest at the top. Analysts spend their morning resolving real issues, not building lookups. Treasury sees reliable balances early and can release idle cash.
Same bank, same people, very different day.
Frequently Asked Questions
What is the difference between nostro and vostro accounts?
They are two sides of the same account. A nostro is the account you hold with another bank. A vostro is the account another bank holds with you.
How often should nostro reconciliation be done?
Daily at minimum. Banks with high volumes or active treasury operations increasingly aim for intraday reconciliation.
What is a nostro break?
A break is an unmatched item between your internal records and the correspondent bank’s statement, which needs investigation and resolution.
Which statement formats are used in nostro reconciliation?
Common ones include SWIFT MT940, MT950, and the ISO 20022 camt.053 message, along with proprietary or manual formats from some banks.
Can nostro reconciliation be fully automated?
Most matching can be automated, and a good platform handles the majority of entries without human involvement. Exceptions still benefit from expert review.
Is automation only for large banks?
No. Smaller banks, fintechs, and payment companies also benefit, especially as cross-border volumes grow.
Final Thoughts
Nostro reconciliation may happen in the background, but its impact is front and center: on liquidity, risk, compliance, and customer trust. As cross-border payments accelerate and standards evolve, relying on spreadsheets and manual effort is a growing liability.
Automation turns nostro reconciliation from a daily scramble into a controlled, transparent, and efficient process. Banks that make the shift gain faster insights, fewer surprises, and teams free to focus on what truly matters.
Ready to Automate Your Nostro Reconciliation?
See how autoReconciliation can help your team match faster, resolve breaks sooner, and gain real-time visibility across every nostro account. Book a free Demo today.